

Money Eco: Budget / Expense
Apponance, Inc.
- 4.7
- 11.00 Reviews
- 10.00K
- Downloads
- Free
- Price
Screenshots
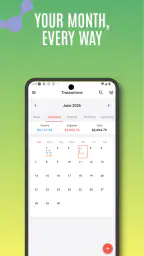
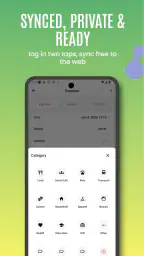
Money Eco: Budget / Expense Pros and Cons
Pros
- Simple interface makes daily expense tracking quick and approachable.
- Useful budget categories help organize spending more clearly.
- Supports better awareness of recurring and unnecessary expenses.
- Suitable for users who want a lightweight personal finance tool.
- Can encourage consistent saving through regular spending reviews.
Cons
- May feel too basic for users needing advanced financial planning tools.
- Manual data entry can become repetitive for frequent transactions.
- Budget insights depend heavily on accurate and consistent input.
- Limited features may not suit households managing shared finances.
- Users should review privacy details before entering sensitive financial data.
 Analysis by All-app
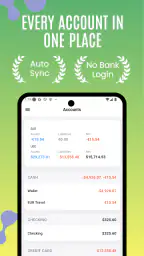
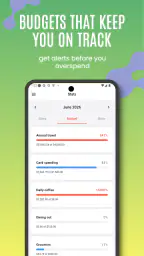
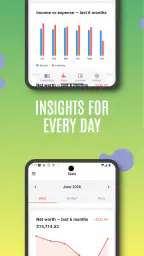
Money Eco: Budget / Expense is the kind of finance app I would suggest to someone who wants a clearer view of everyday spending without turning money management into a second job. Developed by Apponance, Inc., it focuses on recording expenses, organizing a personal budget, and turning those entries into visual reports. That sounds simple, but simplicity is exactly where its appeal lies: the app gives me a place to build a repeatable habit instead of pushing me toward complicated financial planning.
I approached it as a practical personal finance tracker, not as a replacement for a bank app or a full accounting package. Its role is to help me understand where money goes, notice patterns, and make more deliberate choices before the month disappears. The app is free to start, is rated for Everyone, and has reached over ten thousand installs. Its average rating is 4.7 from around fifty ratings, which suggests a positive reception while still representing a relatively small user base.
Building a reliable money routine
The most useful way to begin is to treat Money Eco as a daily log rather than something I open only after overspending. I would enter a purchase soon after making it, choose the relevant category, and use the accumulated record to review the bigger picture later. That small change in timing matters. When I wait several days, cash purchases and minor card transactions become easy to forget, and the report becomes less trustworthy.
A realistic example is a normal weekday with a morning drink, public transport, lunch, and a grocery stop on the way home. None of those purchases feels dramatic on its own. Once they are recorded together with similar entries across the week, however, the visual report can show whether food, travel, or spontaneous shopping is taking more room than expected. I find this more helpful than relying on a vague feeling that I am “spending too much.”
My preferred starting routine would be to enter transactions at the same time each evening, then do a short review at the end of the week. The daily step keeps the information fresh, while the weekly review turns individual purchases into a decision-making tool. I would not try to create a perfect budget on the first day. It is better to establish consistent categories and learn from actual behavior before setting strict limits.
This approach also clarifies what the app is and is not. Money Eco helps me record and visualize personal spending; it does not remove the need for judgment. A report can reveal that entertainment costs are rising, but I still have to decide whether that is a problem, a temporary event, or a worthwhile priority. The app supports that conversation with myself rather than making the decision for me.
Choosing categories that remain useful
One of the easiest ways to make a budgeting app frustrating is to create too many categories. I would keep the first setup broad enough to use quickly: food, transport, household, subscriptions, leisure, health, and savings-related goals where appropriate. The exact arrangement should match my life, but the principle is the same: a category is useful only when it helps me answer a question later.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
For example, separating groceries from restaurant meals can reveal a practical choice, while splitting every type of snack into a separate label may create work without adding insight. I would also avoid changing category names repeatedly. Consistency makes the visual history easier to compare, especially when I return to older entries and want to see whether a pattern is improving.
A less obvious benefit of this restrained setup is that it exposes ambiguous spending. If I keep finding purchases that do not fit anywhere, that may indicate a missing category or a spending habit I have not understood yet. Instead of immediately adding several new labels, I would collect those entries temporarily and decide whether they represent a genuine pattern. This keeps the tracker tidy and prevents the budget from becoming a maze.
Reading the visual reports with some discipline
The visualization is most valuable when I use it to ask focused questions. Rather than staring at a chart and hoping for a revelation, I would compare categories, look for recurring pressure points, and check whether a change in behavior actually appears in the record. A report becomes actionable when it leads to a small experiment, such as reducing takeaway meals for a week or moving a recurring payment into its own category.
I would also be careful not to confuse a large category with a wasteful one. Housing, groceries, or transport may dominate a report because they are necessary. The more useful question is whether the amount is expected, whether it varies unusually, and whether there is a realistic adjustment available. Money Eco can make that distinction visible, but it cannot provide context that I have not entered.
Settings and habits that make the app easier to live with
Before using the tracker seriously, I would spend a few minutes checking the available settings and making the interface fit my routine. The important choices are not about decorating the app; they are about reducing friction. If a setting affects how quickly I can add an expense, how categories are arranged, or how reports are viewed, it deserves attention because repeated small delays are enough to break a budgeting habit.
I would first decide whether the default structure reflects the way I actually think about money. If the app opens to a view that makes recent expenses easy to reach, I would keep that as the main starting point. If I can arrange categories or related options in a more familiar order, I would do that once and then stop adjusting things. Constantly redesigning the setup can feel productive while avoiding the more important task of recording transactions.
The current version is 7.1.0, and the app supports Android 7.0 or later. That makes it accessible on a wide range of Android devices, including older phones that may not run newer finance tools comfortably. Still, I would keep the application updated when an update is available, particularly for a finance app where reliability matters more than having the newest visual style.
There is also a useful distinction between settings that improve speed and settings that merely add detail. I would prioritize anything that reduces the number of steps needed for a common entry. By contrast, optional customization should earn its place: if it makes a report clearer or a recurring review easier, keep it; if it only creates more choices, leave it alone.
Making the first week deliberately simple
For the first week, I would record everything without trying to judge every purchase immediately. This creates a baseline. If I begin by criticizing each coffee or impulse purchase, I may stop logging altogether. A neutral first pass gives me a more honest picture and makes the later budget decisions less emotional.
At the end of that week, I would mark three observations: one category that is predictable, one that is larger than expected, and one that is difficult to classify. That exercise is more useful than setting arbitrary limits. It tells me where the app can help most and where my own spending structure needs clarification.
Another practical tip is to review entries after a major change in routine. A holiday, a move, a new commute, or a change in working hours can make old budget assumptions irrelevant. Rather than deleting the whole structure, I would keep the categories that still make sense and adjust the ones tied to the previous routine. This preserves continuity while acknowledging that spending patterns change.
Handling the cost of convenience
The app itself is free, which makes it easy to try without committing money upfront. It also includes in-app purchases ranging from $0.99 to $14.99 per item. I would treat those purchases as optional decisions rather than part of the basic reason to install it. Anyone who is testing a budgeting habit should first see whether the core workflow fits before paying for anything beyond it.
This is especially important because the value of a finance tracker comes from continued use, not from collecting every available option. If a paid item clearly removes a repeated annoyance, it may be reasonable for a committed user. If I am still forgetting to enter transactions, spending more will not solve the underlying problem. The best investment at that stage is a simpler routine.
Faster patterns for experienced use
Once the basic habit is stable, I would look for repeatable patterns rather than trying to make every entry elaborate. The fastest workflow is usually the one that matches the purchases I make most often. Common expenses should be recognizable immediately, while unusual transactions can receive more attention during the weekly review.
One pattern I find effective is a two-speed system. I enter routine purchases quickly with a clear category, then pause for larger or unusual expenses. This prevents a small purchase from becoming a five-minute accounting exercise, while still protecting the accuracy of meaningful transactions. It also makes the app feel less demanding, which is important when I am using it every day.
A second pattern is to use the report as a checkpoint instead of a punishment. If the food category rises, I would not simply declare the month a failure. I would identify whether the increase came from groceries, restaurants, delivery, or a one-off event, then choose one adjustment. The next review can show whether that adjustment worked. This turns Money Eco into a feedback loop rather than a record of mistakes.
A third useful habit is to separate observation from planning. During entry, I record what happened. During review, I decide what should change. Mixing the two can slow down logging and encourage emotional decisions. Keeping those stages separate lets me maintain accurate history while still using the reports to plan the next week.
Using recurring life events as review prompts
I would attach reviews to events that already happen: the end of a workweek, a payday, a regular grocery trip, or the beginning of a new month. The app does not need to become a separate appointment in my life. When a familiar event prompts a quick look, the habit is easier to maintain than a vague promise to “check finances more often.”
For someone sharing household costs, the app can also support a conversation, provided both people agree on what is being recorded and how categories are interpreted. I would not assume that one person’s entries represent the entire household unless the process is consistent. The strongest use here is not surveillance; it is creating a shared vocabulary for discussing recurring expenses and priorities.
For a student or someone with irregular income, I would focus less on rigid monthly targets and more on separating essential from flexible spending. A visual record can still help, but the review should account for uneven cash flow. A fixed limit that ignores income timing may create unnecessary stress, whereas a category-based view can show which costs are genuinely adjustable.
Where the app reaches its limits
Money Eco is not the right choice for everyone. If I wanted automatic bank synchronization, investment performance, tax preparation, shared real-time accounts, or detailed business bookkeeping, I would look for a specialized service instead. A manual expense tracker can be more deliberate, but it also depends on my consistency. People who expect their transactions to appear automatically may find the workflow too hands-on.
Manual entry has another trade-off: it gives me a chance to think about each purchase, but it creates room for omissions. A forgotten cash expense or a delayed entry can distort the report. I would therefore avoid treating the displayed totals as exact financial records unless I had maintained the habit carefully. For serious reconciliation, a bank statement or dedicated accounting tool remains the better reference.
The visual reports can also encourage false precision. A clean chart may look authoritative even when categories are inconsistent or entries are missing. I would read the trends as guidance, not as a complete financial diagnosis. The app is strongest when the data is regular and the questions are practical; it is weaker when I need formal records or complex financial modeling.
There is a privacy-related behavioral trade-off as well. Even without discussing technical policies, any finance app requires me to decide how much personal spending information I am comfortable entering. I would start with the minimum detail needed to make useful decisions and avoid recording sensitive notes that do not improve the budget. That keeps the tracker focused and reduces unnecessary exposure if someone else views the phone.
Who should choose another tool
I would skip this app if my main goal were managing several bank accounts from one dashboard or tracking investments alongside daily expenses. I would also choose a different option for a business with invoices, reimbursements, payroll, or formal reporting requirements. Those tasks need structures that go beyond a personal budget and expense log.
On the other hand, I would consider Money Eco a sensible fit for someone who wants to understand everyday spending, prefers manual control, and benefits from visual feedback. It is particularly suitable for a person who has tried a spreadsheet but found it too cumbersome, or for someone who wants more structure than a notes app provides without adopting a full financial suite.
The comparison with a spreadsheet is revealing. A spreadsheet offers almost unlimited customization, but it asks me to design formulas, layouts, and reports. Money Eco is more focused and likely easier to use repeatedly for ordinary expenses. A notes app is faster for a single reminder, but it does not provide the same organized view of patterns. A bank app may show transactions, yet it often reflects account activity rather than the personal categories and spending questions I want to examine.
My verdict after settling into the workflow
What I like most about Money Eco: Budget / Expense is its clear purpose. It does not need to become an all-in-one financial command center to be useful. When I use it consistently, it gives everyday spending a shape I can understand, and the visual reports make small habits easier to discuss than a pile of individual transactions.
The main limitation is equally clear: the app cannot compensate for missing entries or an unrealistic budget. Its usefulness depends on a modest amount of discipline. I would recommend starting with a small category system, entering routine purchases quickly, and reserving deeper analysis for a weekly review. That combination gives the app a fair chance to prove its value without making money management exhausting.
Apponance, Inc. has positioned this as a finance app for money management, budgeting, expense tracking, and personal finance visualization. In my view, it succeeds best at the personal, everyday end of that description. It is not the tool I would choose for advanced financial administration, but it is a practical companion for noticing where money goes and turning that knowledge into one manageable change at a time.
With a free entry point, Everyone content rating, and support for Android 7.0 or later, it is easy to test on a compatible device. I would install it with one specific goal rather than expecting a complete financial transformation: record a normal week, review the report honestly, and see whether the categories help me make a better decision. The real strength is not the chart by itself, but the repeatable habit built around it.
My final recommendation is therefore positive but targeted. Choose Money Eco if you want a straightforward manual tracker with visual feedback and are willing to participate in the process. Look elsewhere if automation, account aggregation, or professional records matter more than personal awareness. Used within its proper limits, it offers a calm and accessible way to turn scattered purchases into information I can actually use.
Frequently Asked Questions
What is Money Eco: Budget / Expense used for?
Money Eco: Budget / Expense is designed to help you organize personal finances in one place. You can record income and spending, categorize transactions, monitor where your money goes, and compare expenses with your available budget. After testing the app, its main value is the simple overview it provides, especially for users who want a clearer picture of everyday financial habits without using complicated accounting software.
Is Money Eco: Budget / Expense suitable for beginners?
Yes, the app is generally suitable for beginners because its purpose is easy to understand and the main functions focus on adding transactions, creating categories, and checking summaries. New users may need a little time to decide how to organize recurring bills, cash purchases, and different accounts, but the learning curve is not demanding. It works best when transactions are entered consistently rather than only occasionally.
Does Money Eco: Budget / Expense connect to bank accounts automatically?
Users should not assume that Money Eco: Budget / Expense automatically connects to every bank or imports transactions without configuration. Availability of synchronization, if offered, can depend on the app version, region, device platform, and supported financial institutions. Before downloading or relying on it for complete records, check the current store description and privacy information to confirm whether entries are manual, imported, or synchronized.
Is my financial information safe in Money Eco: Budget / Expense?
Because the app can contain sensitive information about income, purchases, and financial routines, privacy should be considered before use. Review the permissions, privacy policy, backup options, and any account or cloud-sync requirements shown in the current version. Avoid entering unnecessary banking credentials or highly confidential details unless the app clearly explains how they are protected, stored, and removed.
Does Money Eco: Budget / Expense cost anything to use?
The price and available features may vary between Android and iOS, as well as between free and premium versions. Check the official store listing before downloading to see whether the app includes advertisements, optional purchases, subscriptions, or limitations on categories, reports, backups, or devices. If a trial is offered, verify its renewal terms so you are not surprised by an automatic charge after the trial ends.


